


Consumer Economy
- Industrial Production (INDPRO) 103.1 +0.02 (+0.02% m/m)
- Retail Sales (RSAFS) 773.9B +9.5B (+1.24% m/m)
Industrial production was mostly unchanged.
New all-time high for Retail Sales (unadjusted for inflation). Annualized, it was an increase of 14.9%. Sounds like it might be a good actual-inflation metric.
Cherry-picked m/m changes (from census.gov) – requires downloading a spreadsheet and then calculating. Compare vs the 1.24% overall m/m increase:
- Gasoline Stations: +2.97% m/m
- Nonstore Retailers: +2.52% m/m
- Misc Store Retailers: +1.82% m/m
- Electronics/Appliance: +1.53% m/m
Credit & Rates
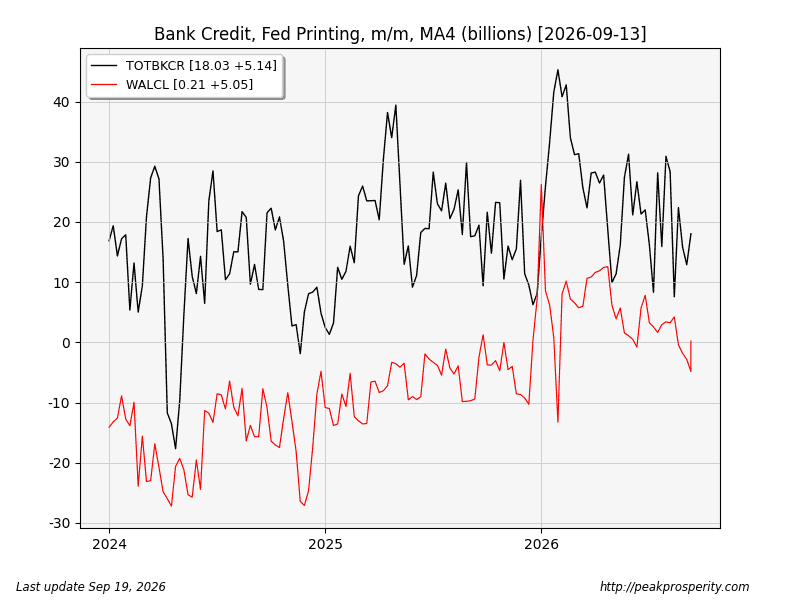
- Total Bank Credit (TOTBKCR) 19.87T +31.1B (+0.16% w/w)
- Fed Balance Sheet (WALCL) 6.75T +5.9B (+0.09% w/w)
- US 30 Year Mortgage Rate (MORTGAGE30US) 6.95% +19 bp
- 3-Month Treasury (DGS3MO) 4.08% +1 bp
- 1-Year Treasury (DGS1) 4.41% +6 bp
- 10-Year Treasury (DGS10) 5.00% +4 bp
- 20+ Treasury ETF (TLT.N) +0.47% w/w
- US Confidence (AAA10Y) 1.0% -7 bp
The Fed raised rates by 25 basis points on Fed Wednesday, kicking off a bunch of market responses that started at 14:00 Eastern. The press conference happened at 14:30. My summary of what Warsh said, below:
FOMC Press Conference, September 16, 2026 [28 m]
- A Fed rate increase won’t open the strait of hormuz.
- Warsh says he is hard pressed to describe current financial conditions as restrictive
- Trends matter [i.e. moving averages – like the MA4], not individual data points
- If we have “full employment”, then “stable prices” are what Warsh will target.
- Economy is growing (GDP, full employment), so price stability was the target; q.e.d. rate increase.
(source – youtube)
Bank credit grew substantially this week; the MA4 is now back to 18B, which is almost not-deflationary. The Fed printed money too, which took the MA4 to just above zero.
Short-rates suggest more rate increases are ahead. The 1-month is dead even with the fed funds rate, the 3-month is 20 basis points higher (hinting at a possible rate increase at the next meeting), and the 6-month is 39 basis points higher, hinting at maybe 2 rate increases in the next 6 months. At the longer end, the changes were mild, but the 10-year ended the week right at 5%, around a 100 basis point rise since the start of the Endless War.
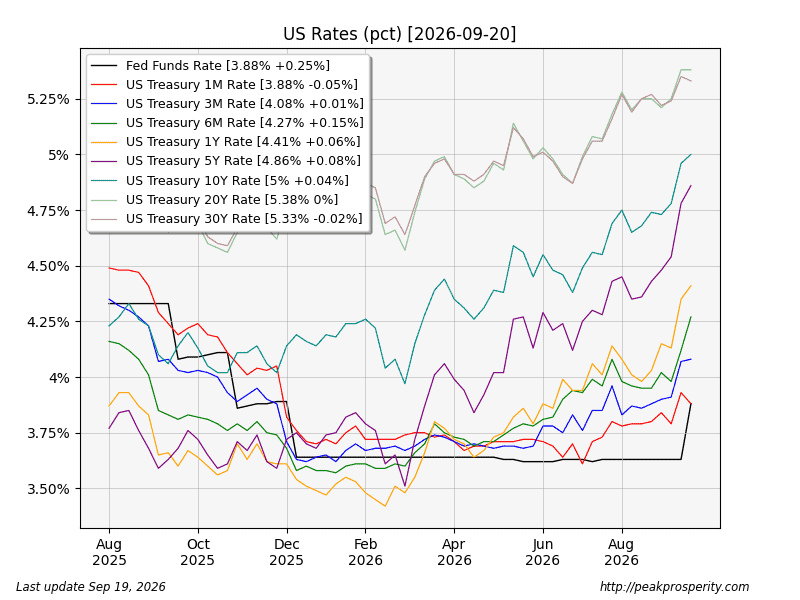
This week the 20-year was mostly unchanged; TLT moved higher [+0.47%], but it was a pretty mild move compared
 by westcoastjan

