


Consumer Economy
UM Consumer Sentiment Survey NSA (UMCSENT); 48.1 -3.60 (-6.96% m/m)
Consumer sentiment fell below 50 again – the little people don’t think the economy is BOOMING.
A happy range is 90-100 – seen a million years ago, during Trump 1.0, when he told everyone that Endless Wars were stupid. That Trump 1.0 guy was pretty smart, it turns out.
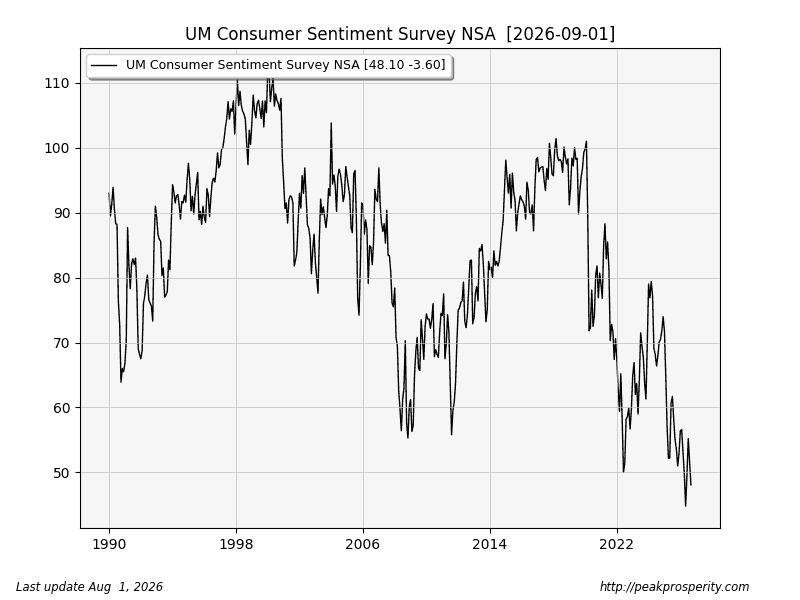
Credit & Rates
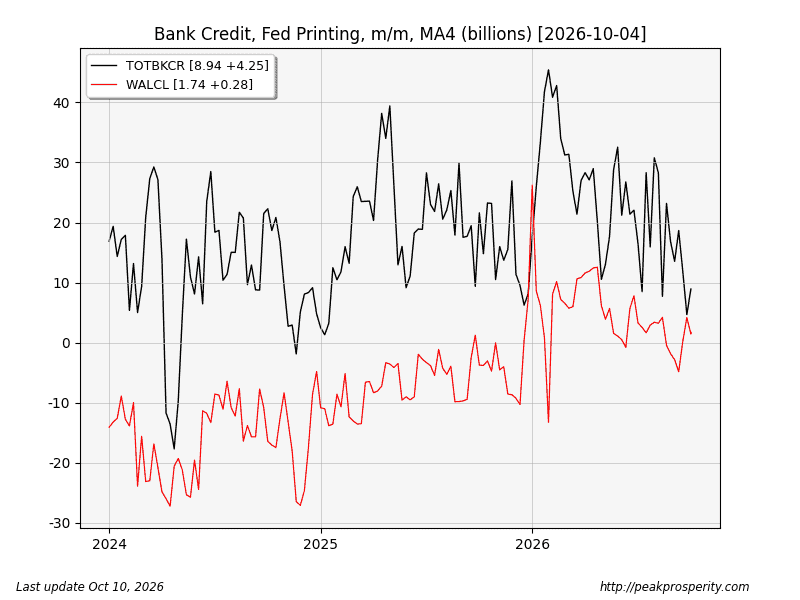
- Total Bank Credit (TOTBKCR) 19.88T +20.1B (+0.10% w/w)
- Fed Balance Sheet (WALCL) 6.75T +4.5B (+0.07% w/w)
- US 30 Year Mortgage Rate (MORTGAGE30US) 7.40% +12 bp
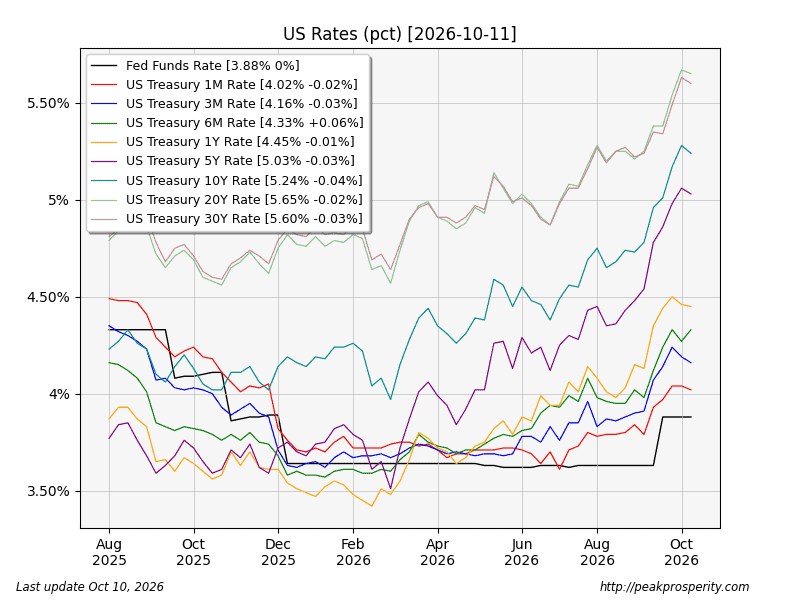
- 3-Month Treasury (DGS3MO) 4.16% -3 bp
- 6-Month Treasury (DGS6MO) 4.33% +6 bp
- 1-Year Treasury (DGS1) 4.45% -1 bp
- 10-Year Treasury (DGS10) 5.24% -4 bp
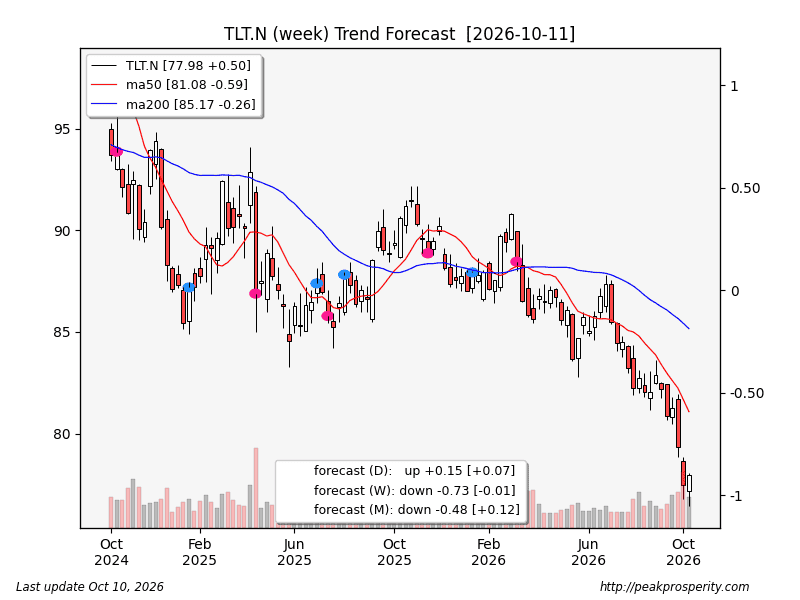
- 20+ Treasury ETF (TLT.N) +0.65% w/w
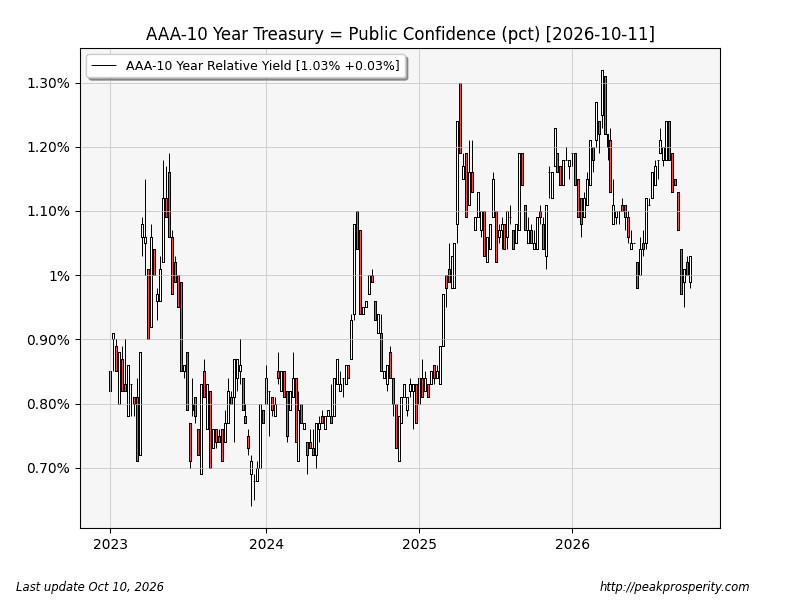
- Public Confidence (AAA10Y) 1.03% +3 bp w/w
Bank credit expanded this week – although at 8.94, the MA4 is still way below what’s necessary – and the Fed printed 4.5B. We got a bounce, but no change yet in the deflationary trend.
Mostly rates inched lower except for the 6-month, which moved higher. The 3-month at 4.16% suggests maybe one Fed rate increase within that time period – and it is effectively providing a rate increase to the market. If the short rates continue dropping, to me that’s a “recession indicator”. We will have to see if short rates continue moving lower.
TLT managed to bounce higher – after hitting a new all-time low on Wednesday. Most of the gains came Thursday and Friday. TLT managed to close back above the 9 MA (not shown) – but remains in a weekly/monthly downtrend. If this is a trend change rather than a blip, a higher close next week (a “swing low”) is something to look for.
Confidence in Treasuries vs corporates inched higher. It’s still not at a great level, but the decline has stopped, at least for now.
CME Fedwatch Tool projects an 18% chance of one rate increase at the October 28th meeting.
Currencies
The buck climbed 0.31 [+0.30%] to 102.02 – moving higher for the 4th straight week. These levels for DX were last seen 18 months ago. The winners-losers map was curious; Euro was the biggest loser, alongside the Indian Rupee, while AUD and KRW improved.
Looking at the daily chart, the buck
 by peak1970

