


Consumer Economy
- Retail Sales (RSAFS) 748.2B +1.6B (+0.21% m/m)
- Industrial Production (INDPRO) 103.4 -0.45 (-0.43% m/m)
Industrial production (an index) declined, moving down off the recent (8-year) high. It is just one month, but if it continues, that’s recessionary.
Retail Sales climbed just 2.52% annualized. That’s not keeping up with inflation.
Credit & Rates
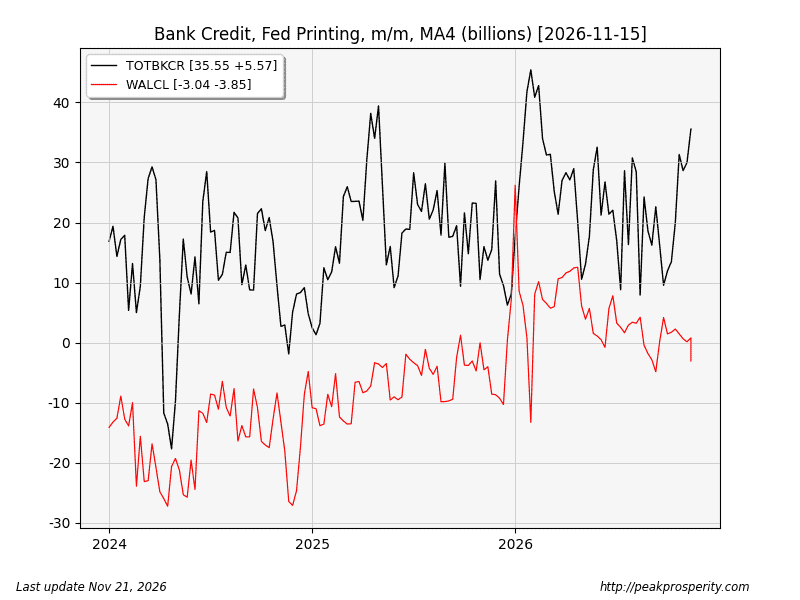
- Total Bank Credit (TOTBKCR) 20.13T +62.3B (+0.31% w/w) (prior +0.24% w/w)
- Fed Balance Sheet (WALCL) 6.74T -17.4B (-0.26% w/w) (prior +0.16% w/w)
- US 30 Year Mortgage Rate (MORTGAGE30US) 7.28% +17 bp
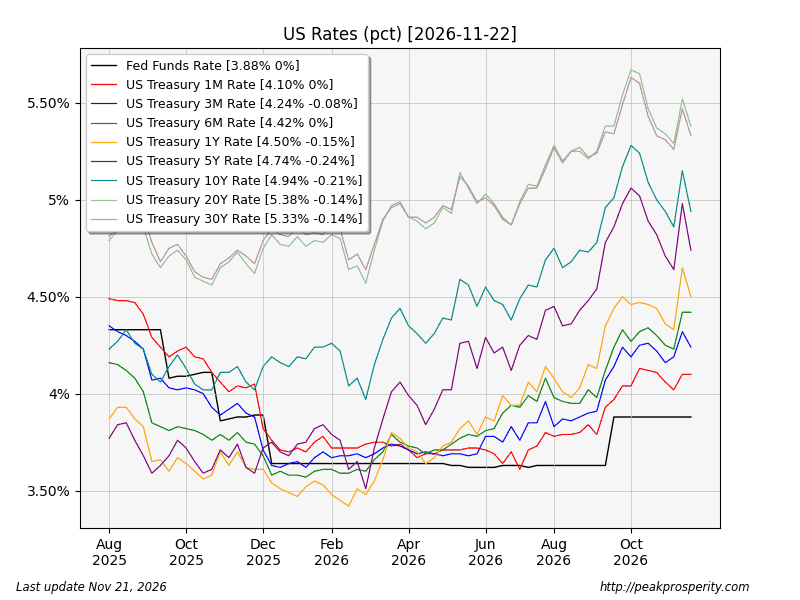
- 3-Month Treasury (DGS3MO) 4.24% -8 bp
- 1-Year Treasury (DGS1) 4.50% -15 bp
- 5-Year Treasury (DGS5) 4.74% -24 bp
- 10-Year Treasury (DGS10) 4.94% -21 bp
- 30-Year Treasury (DGS30) 5.33% -14 bp
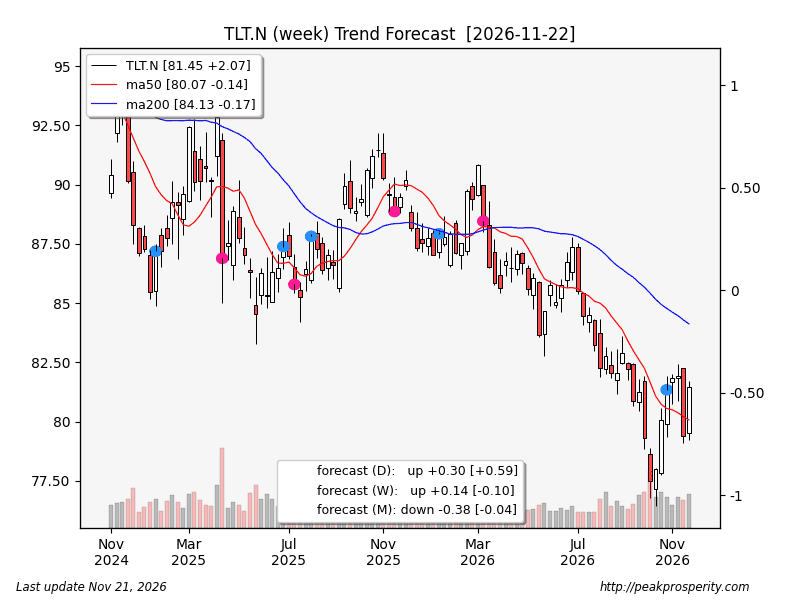
- 20+ Treasury ETF (TLT.N) +2.61% w/w (prior -3.10% w/w) -7.17% y/y
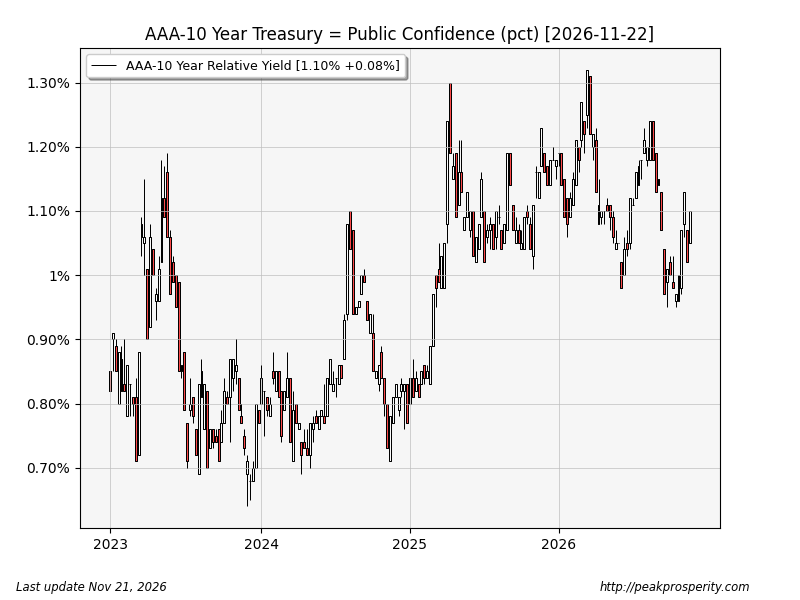
- Confidence in US Government (AAA10Y) 1.10% +8 bp
This week saw a massive increase in bank credit (16% annualized), while the Fed reverse-printed 17 billion.
Sector changes in bank credit:
- Commercial/Industrial: +26B
- Treasury & agency securities: +25.8B
- All other loans and leases +10.55B
- Real estate loans: +1.94B
- Consumer loans: –0.31B
It seemed to be about the banksters buying Treasuries, along with commercial/industrial. Some growth in data centers (all other loans/leases) – but consumers saw deflation.
Treasury rates mostly moved lower – especially at the long end. Treasuries are back to a safe haven play. Even with the high inflation numbers, money is back to moving into longer-dated Treasurys – less so for the shorter-dated Treasurys.
The drop in long-rate bonds caused the 20+ Treasury ETF to jump higher, up 2.61% – mostly eliminating last week’s losses. Things sure are choppy in the bond space right now. Inflation + market panic = a hard-to-predict trade in longer-dated bonds. TLT did manage to close back above the 50 MA, which is a positive trend change.
Confidence in the US government increased this week, rising 8 bp to 1.10%, erasing much of last week’s losses. Perhaps the bubble pop is making those Microsoft bonds look a bit less attractive?
CME Fedwatch Tool projects an 89% chance of one (25 bp) increase on the December 9th meeting – gone are the hints of a 50 bp increase.
Currencies
The buck rose 0.42 [+0.41%] to 103.75 – most of the move
 by randommike

