


Consumer Economy
- Auto/Light Truck Sales (ALTSALES) 15.5M -433.0K (-2.71% m/m
- Nonfarm Payrolls (PAYEMS) 159.3M +165.0K (+0.10% m/m)
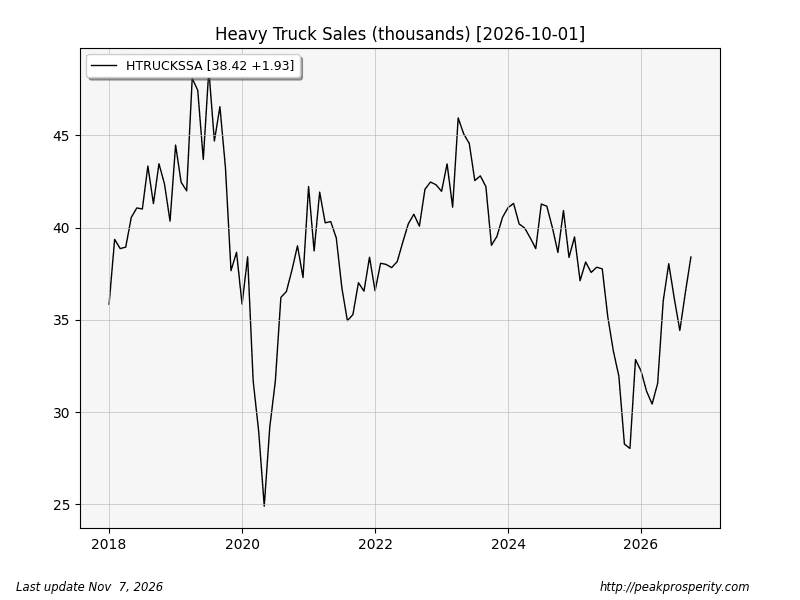
While auto/light truck sales moved lower – not great news – the recession-indicator “Heavy Truck Sales” moved up to a new short-term high. I’m guessing all that truck activity might be related to data center construction.
Payrolls
Employment Situation Summary Table B. Establishment data, seasonally adjusted [Column 4]
- Total Nonfarm +165k
- Total Private +159k
- Prof/Bus Services +70k
- Sickcare +55k
- Transportation +25k
- Government +6k
- Leisure -13k
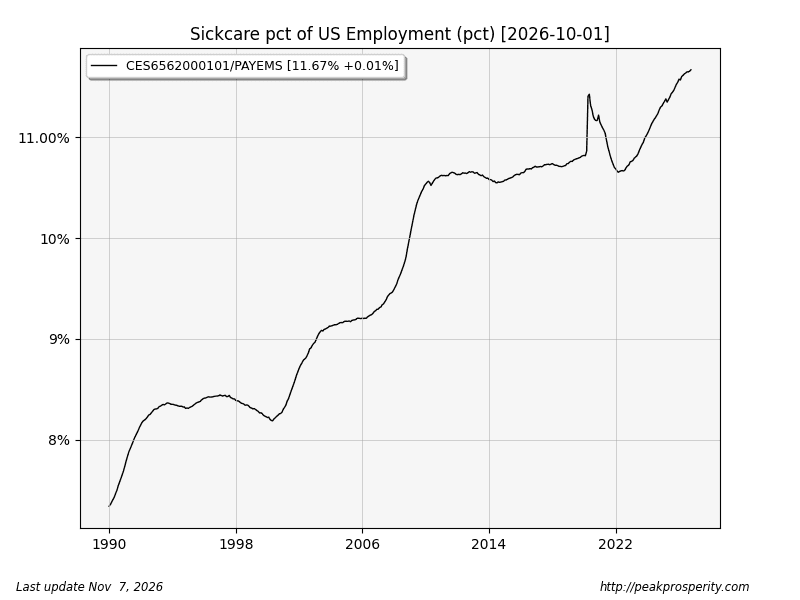
It was a BOOMING jobs market last month, and one-third of the increase came in sickcare. Sickcare has been increasing as a percentage of the US workforce since 1990, and the percentage made yet another new all-time high this month. Doctors are baffled as to why.
Perhaps next I could chart the sickcare percentage alongside the number of shots in the childhood vaccine schedule over time with (maybe) a 5-year delay. If more shots saved Baby & Grandma, the sickcare workforce percentage should be declining…
With a Disability
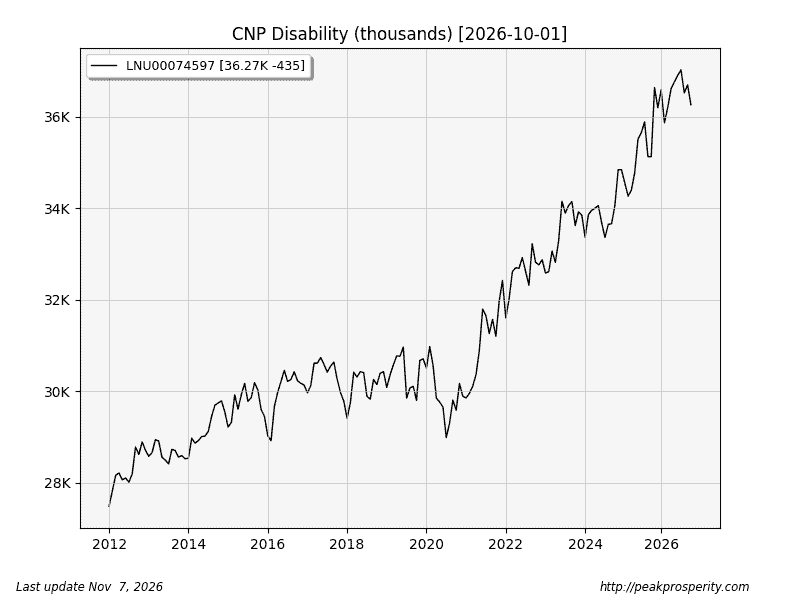
- CNP (LNU00074597) 36.266m -435k -1.19%
- CLF (LNU01074597) 8.795m -267k -2.95%
- EMP (LNU02074597) 8.127m -254k -3.03%
- NILF (LNU05074597) 27.471m -168k -0.61%
Total population with a disability fell again this month. Is that good news? Either the shot victims are being healed, or they are dying and being replaced by …
Native/Foreign born Employment
- Native-born (LNU02073413) 132.12m -64k -0.05%
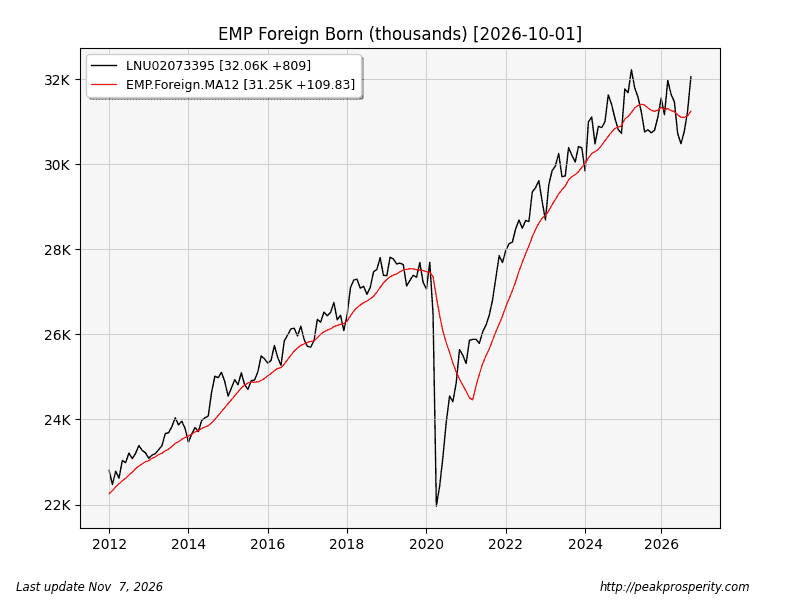
- Foreign-born (LNU02073395) 32.06m +809k +2.59%
Foreign-born employment saw a YUGE increase [+809k +2.59%], while the native-born saw a slight decline [-64k -0.05%]. This was the largest single increase in “October” foreign-born workers in history; second place was in 2021 under Senile Joe at +525k. Maybe the vax-injured native-born are being replaced by the unvaxxed foreign-born?
Regardless, “BOOMING” payrolls seemed to be all about the foreign-born this month.
Credit & Rates
- Total Bank Credit (TOTBKCR) 20.02T +9.5B (+0.05% w/w)
- Fed Balance Sheet (WALCL) 6.75T +2.5B (+0.04% w/w)
- US 30 Year Mortgage Rate (MORTGAGE30US) 7.18% -6 bp
- 3-Month Treasury (DGS3MO) 4.11% -5 bp
- 1-Year Treasury (DGS1) 4.32% -4 bp
- 5-Year Treasury (DGS5) 4.65% -6 bp
- 10-Year Treasury (DGS10) 4.87% -7 bp
- 30-Year Treasury (DGS30) 5.27% -4 bp
- 20+ Treasury ETF (TLT.N) +0.10% w/w
- Confidence in US Government (AAA10Y) 1.13%

