


Credit & Rates
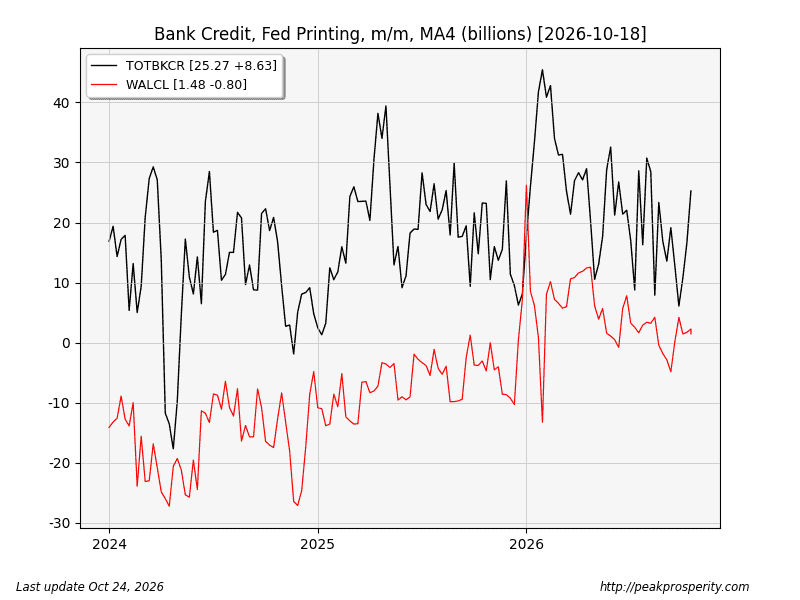
- Total Bank Credit (TOTBKCR) 20.00T +45.6B (+0.23% w/w)
- Fed Balance Sheet (WALCL) 6.75T -2.0B (-0.03% w/w)
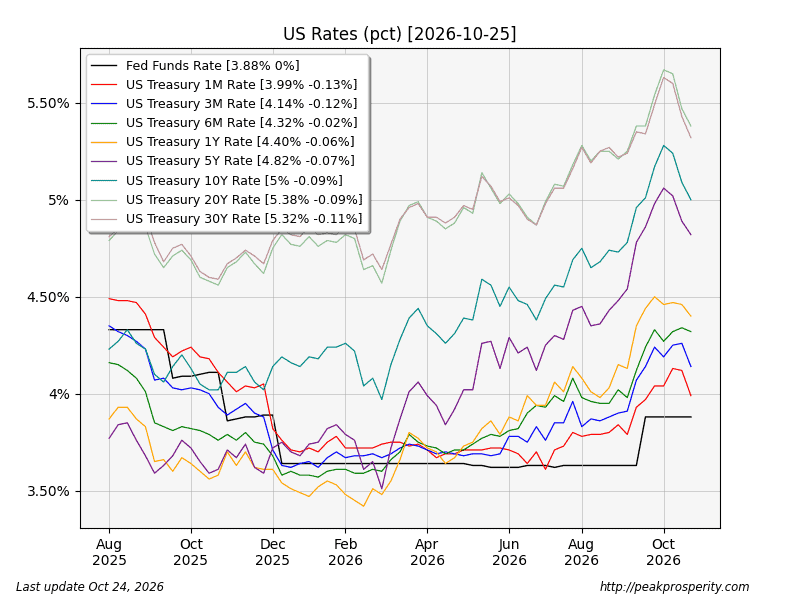
- US 30 Year Mortgage Rate (MORTGAGE30US) 7.32% -8 bp
- 3-Month Treasury (DGS3MO) 4.14% -12 bp
- 1-Year Treasury (DGS1) 4.40% -6 bp
- 5-Year Treasury (DGS5) 4.82% -7 bp
- 10-Year Treasury (DGS10) 5.00% -9 bp
- 30-Year Treasury (DGS30) 5.32% -11 bp
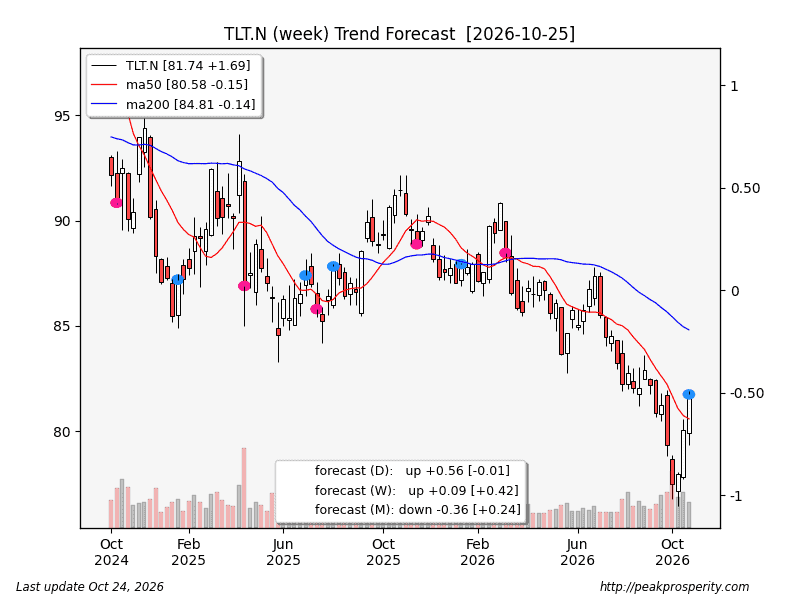
- 20+ Treasury ETF (TLT.N) +1.29% w/w
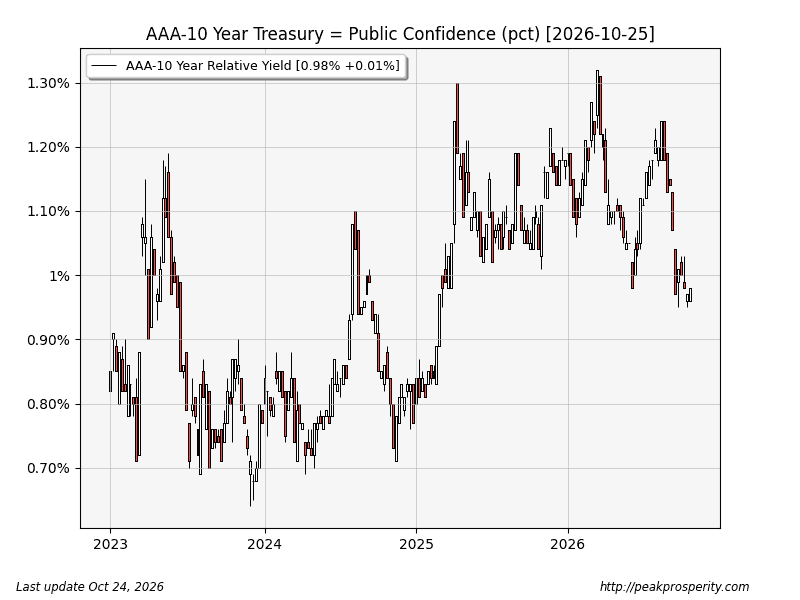
- Confidence in US Government (AAA10Y) 0.98% +1 bp
There was a large expansion in bank credit this week, while the Fed reverse-printed 2B. The biggest chunk (about 19B) of bank credit increase was in the “all other loans and leases” category, which Ed Dowd has said is linked to funding of the AI Bubble. Bank credit growth above 20B is “enough”, and this week – it was 45.6B.
It was another week of falling rates. Are the Twitterati noticing? Ed Dowd thinks we might have seen a cycle high for the 30-year Treasury. To me, that would be a marker for a serious correction in risk assets (SPX, tech, the AI bubble, etc.).
US Long Bond yields peaked on October 7th (30 year). We need more structural technical evidence but a very good chance we have a significant cycle high in yields. [Oct 22]
(source – DowdEdward)
This decline in yield (assuming it’s a safe haven move) seems to be colliding with the YUGE (inflationary) bank credit expansion this week. I’m not sure which one will end up being correct.
TLT rallied 1.29% this week – the third weekly rally in a row – although there was a correction on Friday [-0.49%] going into the weekend. This is the kind of (weekly) gain you get when you hold long bonds when yields decline.
Confidence in US government rose 1 bp this week to 0.98% – not much change, and that is as of Thursday since the FRED series (AAA10Y) always updates with a one-day delay. Even though the long rates have moved significantly lower, confidence in government has barely moved.
CME Fedwatch Tool now projects just a 10% chance of one increase at the October 28th meeting. That’s next week, the day after the election in Israel.
Currencies
The buck was mostly unchanged [-0.01 -0.01%], ending the week at 101.65. That said, there were
 by binkey

