


Consumer Economy
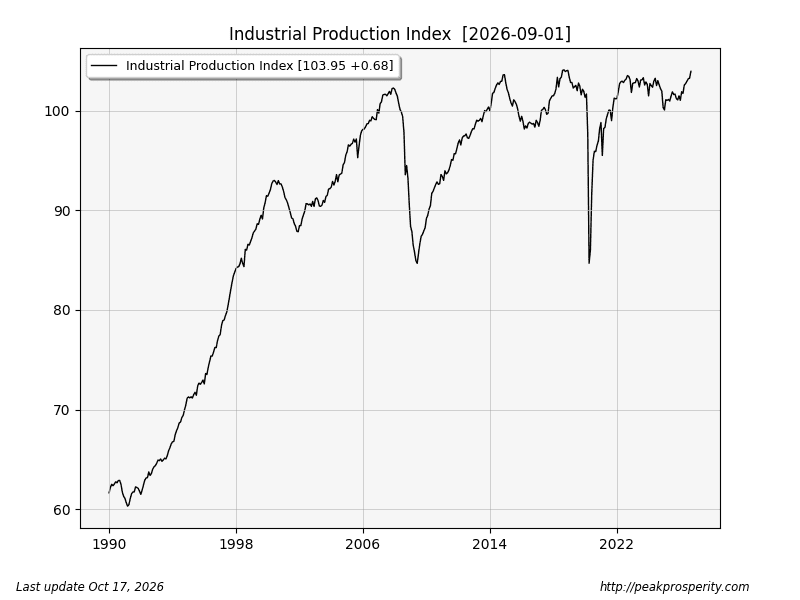
- Industrial Production (INDPRO) 104.0 +0.68 (+0.66% m/m)
- Existing Home Sales (EXHOSLUSM495S) 3.99M +60.0K (+1.53% m/m)
- Retail Sales (RSAFS) 745.0B +5.7B (+0.77% m/m)
- CPI All Urban (CPIAUCSL) +0.65% m/m
- Producer Price Index, All Commodities (PPIACO) +0.96% m/m
Industrial Production (an index) broke out to a new 8-year high this month; we are not far from a new all-time high. This is not recessionary, but I’m not sure if “AI” counts as Industrial Production.
Existing Home Sales at 3.99M units is still chopping sideways near the lows. Breakout would be above 4.3M units.
Retail Sales (a dollar amount): +0.77% m/m, or +9.24% annualized. BOOMING!
Current table: https://www.census.gov/retail/marts/www/marts_current.pdf
- Gasoline Stations: +6.4% m/m
- Furniture: +1.3% m/m
- Food Services: +1% m/m
- Health/personal care: +0.7% m/m
- Food/Bev: +0.4% m/m
- Clothing: +0% m/m
- Misc stores: -3% m/m
Gasoline stations at 6.4% m/m x 12 = 76.8% annualized.
CPI: +0.65% m/m is 7.8% annualized. BOOMING!
CPI release details at https://www.bls.gov/news.release/cpi.t01.htm#cpipress1.f.1
Column 10 (far right); cherry-picked m/m change.
- Fuel Oil: +15.3% m/m
- Motor Fuel: +9.3% m/m
- Items less food & energy: +0.3% m/m
- Used Cars/Trucks: +0.7% m/m
- Hospital Services: +0.7% m/m
- Vaxxident (Auto) Repair: +0.7% m/m
- Airline Fares: +1.2% m/m
Producer Prices (all commodities) at https://www.bls.gov/news.release/pdf/ppi.pdf
Intermediate Demand by Commodity Type; input costs to production +0.96% m/m, +11.52% annualized.
Table B [m/m change]:
Processed Goods:
- Total: +2.5%
- Food/Feeds: +0.4%
- Energy Goods: +10.2%
- Less Food/Energy: +0.5%
Unprocessed Goods:
- Total: +8.5%
- Food/Feeds: +0.8%
- Energy materials: +22.2%
- Nonfood materials less energy: +2.5%
Credit & Rates
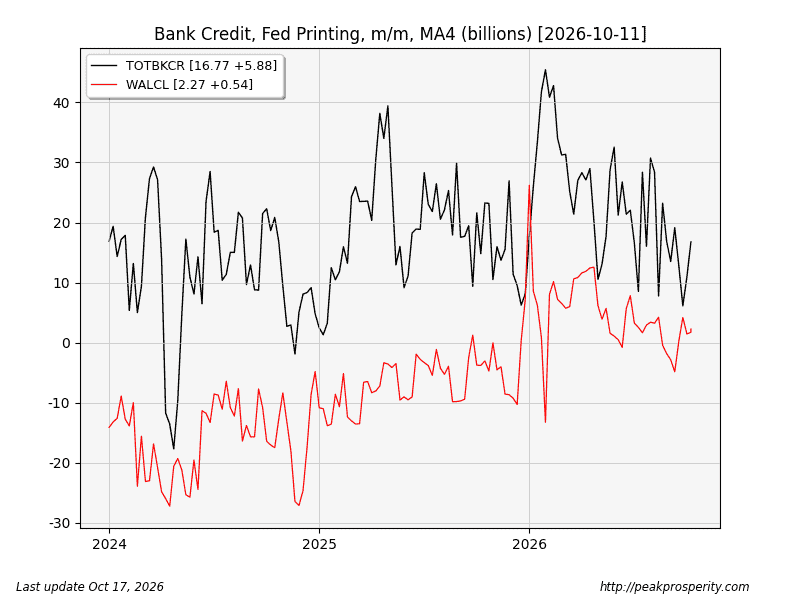
- Total Bank Credit (TOTBKCR) 19.95T +57.1B (+0.29% w/w)
- Fed Balance Sheet (WALCL) 6.76T +8.1B (+0.12% w/w)
- US 30 Year Mortgage Rate (MORTGAGE30US) 7.40% +0 bp
- 3-Month Treasury (DGS3MO) 4.17% -8 bp
- 1-Year Treasury (DGS1) 4.42% -5 bp
- 10-Year Treasury (DGS10) 5.09% -15 bp
- 20-Year Treasury (DGS10) 5.09% -17 bp
- 20+ Treasury ETF (TLT.N) +2.65% w/w
- Public Confidence (AAA10Y) 0.95% -3 bp
Bank credit expanded “enough” this week, while the Fed printed money. The trend remains deflationary, but things have inflated somewhat over the last two weeks.
Rates moved lower, especially at the long end, except for the 6-month, which was mostly unchanged. Tea leaves suggest “just one rate increase within 3-6 months,” but in spite of the massive increase in CPI and PPI, a rate
 by cbandi

