


Something is very wrong in our markets, or ““markets”” as I like to put it, given just how disconnected they’ve become from reality.
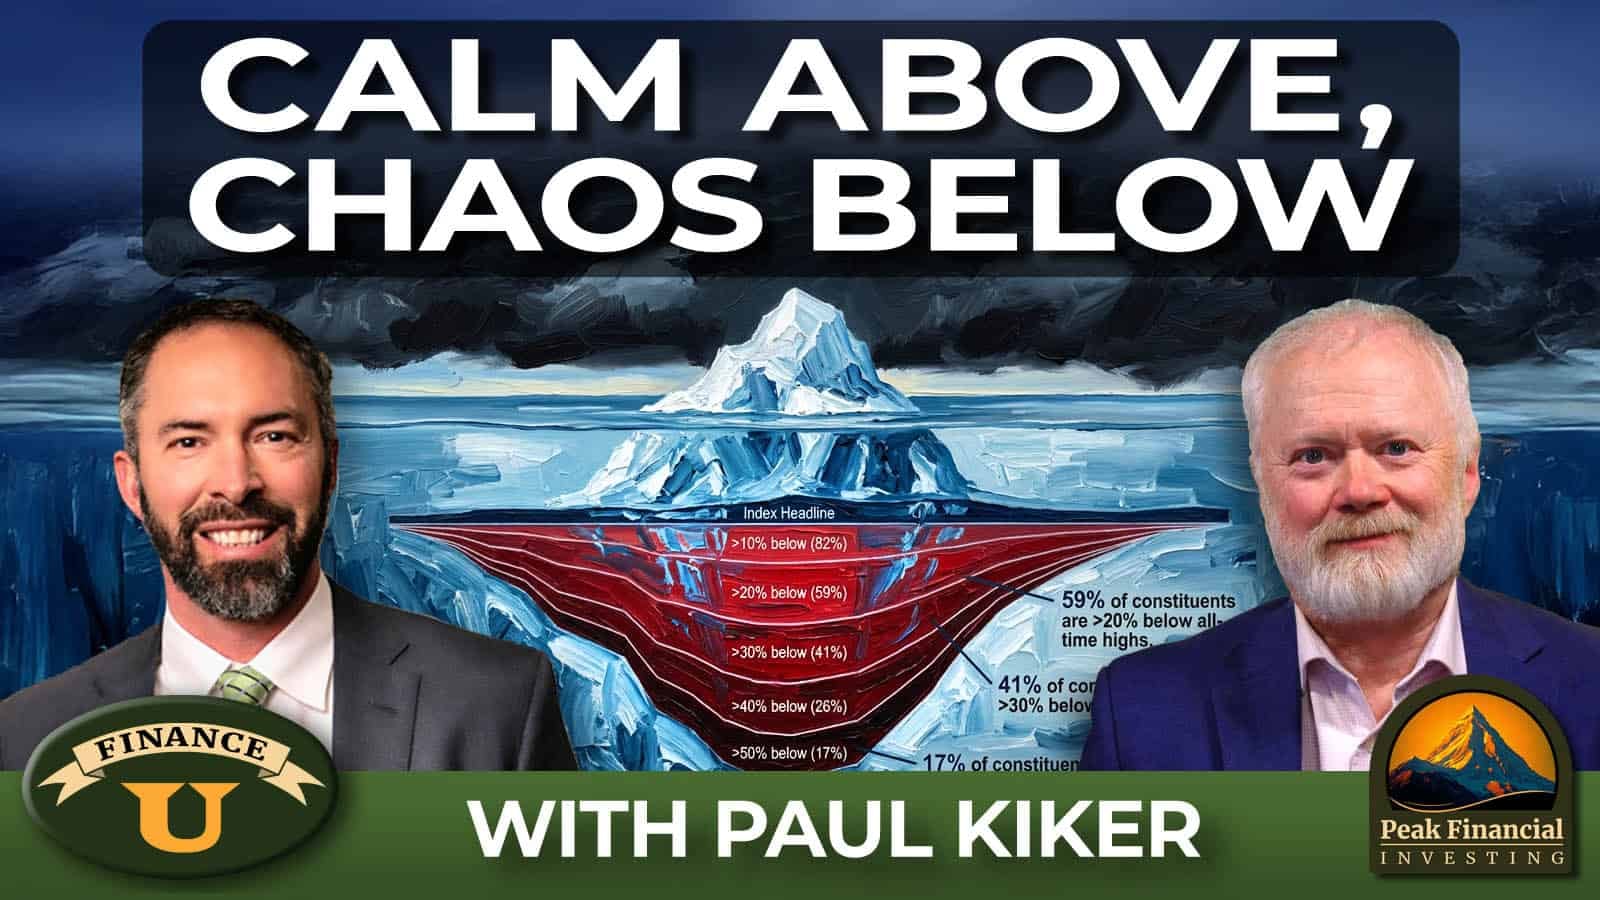
Weirdly, even as the S&P 500 hovers near all-time highs, beneath the surface we discover that 59% of all S&P 500 companies are now in bear-market territory, as they are 20% or more below their recent peaks.
Meanwhile, oil futures prices continue to display profound shenanigans with “somebody” staging daily price attacks. But if you want a barrel of oil today? That’s going to cost you ~$20 more + shipping & handling, which will be another ~$25.
To call this unprecedented would be using that word accurately. The disconnects are greater than have ever been seen before.
Speaking of which, long bonds are also signaling that something severe is on the way. With the 10-year hitting 5.30% and the 30-year hitting 5.70% we’re back to interest rates not seen for 20 or more years. And that’s with massive fiscal deficits and a housing market that is still hugely overvalued from an affordability standpoint.
Paul Kiker tracks a wide variety of indicators, and his list of warning flags is long and growing.
Where does all this lead? Frankly, probably nowhere meaningful until after the midterm elections. Why? Because this administration has shown it is willing to do whatever it takes to force ““markets”” to provide support for political aims.
But those efforts will only cause the imbalances to grow. When these finally give way, I’m expecting fairly large and disorderly corrections in a wide variety of stocks, bonds, and commodities.
Note:
I find AI summaries to be quite useful. So here’s an AI summary of this week’s podcast. I’ll probably start including these going forward, but rest assured I will always be crystal clear when something is written by AI. Otherwise, I write everything that carries my name.
AI SUMMARY:
The three points that carry the episode are these.
- Oil is being held down in the paper market while the physical market is breaking. Tanker strikes in the Strait of Hormuz just had their worst week of the war (12 oil and gas tankers hit through October 5). Dated Brent versus futures has blown out to about $32 a barrel, and freight is adding roughly $20–28 a barrel to get oil delivered. Spot WTI is still near where it was a week into the war. Martenson points to repeated overnight selloffs and a regular midday slam with no news, and reads that as algorithms being pointed at the price, not as a market discovering it.
- Long bonds are the market they cannot control. The 30-year touched 5.7 percent, levels last seen around 2002, and the move is global (US, Japan, UK, France, Germany). Goldman recently called the long end bidless. Treasury has had to run buybacks of old low-coupon paper just to keep the appearance of liquidity. Paul Kiker’s chart shows the 10-year yield having broken successive resistance levels and still accelerating. Hyperscaler investment-grade issuance is large enough that they argue it is crowding out Treasuries.
- The headline indexes and the real economy have split, and the split is being papered over into the midterms. About 59 percent of S&P components were already in a structural bear market (down more than 20 percent from highs), while the cap-weighted index holds up on a handful of names and AI spend. Under that, church fundraisers, dentists, and food pantries are reporting 2008-style tightness, and insurance costs are hitting younger households hardest. On the AI side, only about 2.2 percent of US households pay for it, while Zero Hedge’s tracker of hyperscaler off-balance-sheet liabilities hit $3.8 trillion as of September 30, up $700 billion in three months. Jim Chanos (via Paul Kedrosky) is cited for the claim that this boom checks all four historical bubble boxes at once: credit, government, technology, and real estate.
Chris Paul spend the hour on why the tape does not match the physical world. Oil is the clearest case: worst tanker week of the war, an extreme prompt-versus-futures spread, and shipping that makes “$88 oil” irrelevant if you actually need barrels in Japan, yet the futures chart looks like a wedge going nowhere, with sell programs clustered at odd hours and at noon. They treat that, plus the simultaneous bid in stocks and bonds at 1:35 a.m. on September 29 with no news, as evidence that a lot of price discovery is now algorithmic and politically convenient heading into the midterms, not a human market expressing greed and fear.
The counterweight is bonds. Yields keep stair-stepping higher, the long end has gone bidless enough to force Treasury buybacks, and AI-related debt issuance is competing with the government for the same buyers. Kiker argues that if that yield pressure ever reversed it would be fuel for the indexes, but he does not expect a clean reversal while the Gulf stays hot and refined-product and fertilizer tightness (China, Russia, and India restricting fuel and sulfur exports) keeps feeding cost-push inflation. Around that they note ground-level stress that official inflation misses, the Enron-like feel of circular AI financing, and the practical hedges they keep repeating: stay inside FDIC limits or use Treasury-only cash vehicles, keep brokerage assets in non-margin accounts so they cannot be rehypothecated, and mentally rehearse a 50–60 percent equity or long-bond drawdown rather than assume the narrative holds.
Timestamps
00:00 The Reset Is Coming
01:40 Oil Defies The Headlines
06:34 When Algorithms Replace Markets
10:53 The Bond Market Breaks Down
15:19 Cracks Beneath The Rosy Narrative
19:48 Inflation Hits The Middle Class
23:41 The Invisible Hand At Work
26:44 The Great Taking Gets Closer
30:17 Bonds Are The Big Warning
34:35 The Red Diesel Loophole
37:22 The Middle East Is Still Burning
42:00 The AI Bubble Gets Bigger
48:00 Why Short Sellers Matter
51:38 The $3.8 Trillion AI Problem
54:27 History’s Bubbles Keep Repeating
56:34 Prudence Beats Complacency
FINANCIAL DISCLAIMER:
The information contained in this video and the resources available for download through our affiliated website are not intended as and shall not be understood or construed as financial advice, nor should be interpreted as a solicitation to sell or offer to sell investment advisory services. No person who currently works for or contracts with Peak Prosperity or Peak Financial Investing is an attorney or accountant, nor are we holding ourselves out to be, and the information contained in the video and on the website is not a substitute for legal or tax advice from a professional who is aware of the facts and circumstances of your individual situation. While Peak Financial Investing is a registered investment advisor, please note that this podcast is not intended to be investment advice.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such. We have done our best to ensure that the information provided is accurate and provides what we feel is valuable information. The views expressed are subject to change based on market and other conditions.<
No guests or clients appearing on the podcast receive any form of compensation for their appearance and obtained no other benefit from either Peak Prosperity or Peak Financial Investing.
All investing involves risks including the possible loss of capital. Asset allocation and diversification does not ensure a profit or protect against loss. Please note that out- performance does not necessarily represent positive total returns for a period. There is no assurance that any investment strategy will be successful. All investments carry a certain degree of risk. Dividends are not guaranteed, and a company’s future ability to pay dividends may be limited.
Additional important disclosures for Peak Financial Investing may be found in our Form ADV Part 2A, which can be found at https://adviserinfo.sec.gov/firm/summary/319672.

 by cmartenson