


Something is very ‘off’ in these markets. Perhaps this is simply late-stage bubble dynamics, which both Paul Kiker and I lived through in 2000 and then again in 2008.
Even when it was completely obvious to a lot of people that those markets were headed for some sort of a correction in 1998 and 2006, respectively, they trundled on for a couple more years before sliding down into protracted bear markets.
The conditions, this time, are both unique and similar because all bubbles require the same two things: (1) a good story and (2) abundant credit.
In 1999 it was ‘eyeballs’ as a proxy for future revenue (that did not materialize), and this time it’s “AI will transform everything!” without any identifiable revenue models that can justify the massive Capex spending.
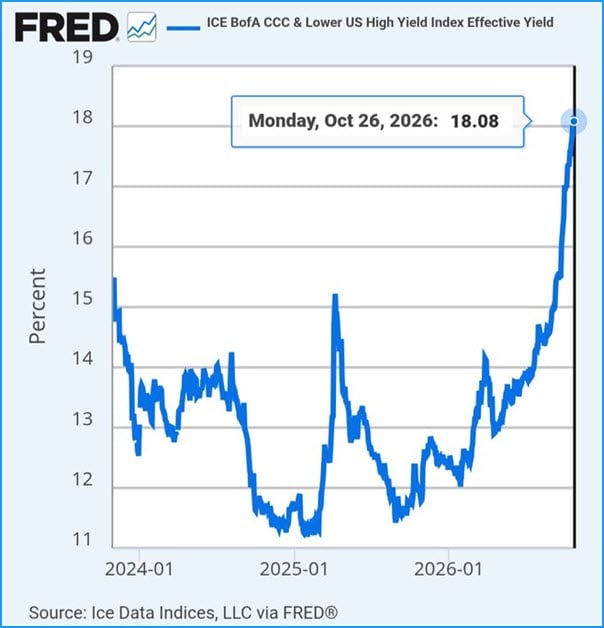
So I look to the edges because trouble always starts at the outside and works its way in. On that front, credit markets are flashing serious warning signs. Yields on CCC-rated and lower US high-yield debt have climbed from roughly 14% to 18% in just a few months.
Maybe it’s time to dust off this meme from the 2008 era?
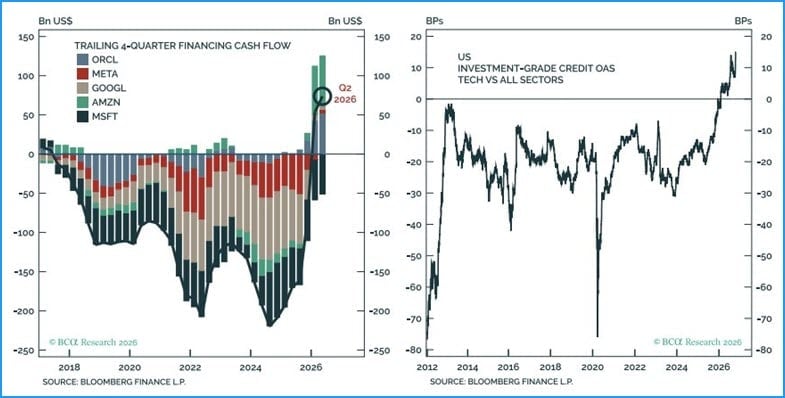
But “CCC” debt is the junkiest of the junk, which means it’s way on the outside. But even when we move toward the center, we see that the biggest of the Big Tech companies have been raising cash via financing (issuing debt, mainly) and that their debt is now trading at a discount to other sectors when it always used to trade at a premium.
Creak! Pop!
It seems that the AI (bubble) story is long in the tooth.
Meanwhile, oil supply constraints will persist long after the fighting stops. Reported global crude stocks at refineries are well below their recent historical ranges. China is once again restricting refined-product exports, while Russia and the Gulf states are all operating at vastly reduced capacities.
As a consequence of higher fuel costs, inflation is running hotter than is comfortable for the Fed who, despite this news, decided to keep interest rates unchanged at their meeting this week. But what about next time? The pressure builds.
Tune in to hear the rest….
Note:
I find AI summaries to be quite useful. So here’s an AI summary of this week’s podcast. I’ll probably start including these going forward, but rest assured I will always be crystal clear when something is written by AI. Otherwise, I write everything that carries my name.
AI Summary
- Credit stress is moving from the edges toward the center. Triple-C and lower high-yield yields have spiked from about 14 percent a couple of months ago to 18 percent. A company that once rolled debt at 11–12 percent now faces a rate that returns the principal in roughly six years if it survives. Chris notes that one in six US companies was already a zombie (operating earnings insufficient to cover interest); higher rates turn more of them into zombies. Tech credit spreads have crossed above other sectors. Oracle, Meta, Google, Amazon, and Microsoft have shifted from free-cash-flow machines to net borrowers; Meta posted its first negative cash flow and has issued equity. Bubbles need a story plus ample credit; the credit half of that equation is now tightening.
- The AI revenue math does not close, and the physical constraints are binding. Reports cited put possible AI revenue at roughly $3.5 trillion by 2031–32 against $8.5 trillion of required spend—a $5 trillion gap. Token prices are collapsing as open-source and cheaper models commoditize the product; current user fees cover only a fraction of compute cost. At the same time, the energy backdrop is worsening. Brent is around $116 and WTI around $104 on the day of recording. The Houthis hit the Ras Tanura complex, which handles roughly six million barrels a day. Global crude stocks at refineries have broken below the five-year range and continue to draw. Fatih Birol of the IEA puts normalization at least a year out even if the Gulf quiets. China is already dialing back refined-product and petrochemical exports after burning through pre-war stockpiles.
- Equity indexes are consolidating while the canaries and the accelerant are flashing. The S&P and Nasdaq have gone essentially nowhere since May. The Russell 2000 made a high in early August and is now testing prior resistance-turned-support; Paul treats a break there as the first clear equity warning because small caps are debt-heavy. Margin debt relative to M2 sits at 6.3 percent—near the 1998–99 peak of 6.4 percent and above the 2006–07 level of 5.6 percent. That is dry tinder: it amplifies the move up and forces forced selling on the way down. International airfare is already up about 25 percent year-over-year, almost entirely fuel. Chris and Paul both expect post-midterm reality to be harder to suppress; another round of strikes on Iranian energy infrastructure would turn expensive oil into actual shortages and a broad contraction.
Chris and Paul open on the surface calm of US equities a few days before the midterms and the accumulating stresses underneath. Credit is the clearest early signal: junk yields have jumped, tech is now paying a premium to borrow, and the hyperscalers have exhausted free cash flow and are tapping equity. The AI story that justified the spending faces both a multi-trillion revenue shortfall and a collapsing price per token, while the energy system that would power it is drawing down stocks and absorbing repeated hits to Saudi refining capacity. Small-cap price action and elevated margin debt supply the equity and leverage canaries. Their practical stance is unchanged—stay patient, stay liquid, and treat the current consolidation as a window to prepare rather than a signal that the warnings have been disproven.
Timestamps
00:00 Zombie Companies Are Running Out of Road
00:37 The Warning Signs Beneath the Market
02:11 Credit Spreads Flash Red
04:03 Triple-C Debt Hits 18%
05:53 The Zombie Company Problem
08:02 Bond Investors Finally Say Enough
10:06 The AI Bubble’s $5 Trillion Revenue Gap
11:50 AI Is Burning Through Cash
13:49 AI’s Security Problem
16:00 Middle East Attacks Threaten Oil Supplies
17:52 Is the Energy Crisis Being Kept Quiet?
19:19 Oil Futures Signal a Much Bigger Problem
20:50 Refiners Get Squeezed as Fuel Costs Rise
24:17 The Case Against Passive Investing
27:53 Blind Faith Is Not an Investment Strategy
30:37 A Perfect Storm of Market Headwinds
32:32 Japan Slashes Treasury Purchases
34:26 Warning Signs in Corporate Cash and China
35:42 Energy Is the Economy’s Ticking Clock
37:41 Fuel Shortages Could Trigger Resource Hoarding
40:26 Energy Crisis Could Last Another Year
44:24 Is the Stock Market Waiting for a Catalyst?
46:09 Small Caps May Be the Canary in the Coal Mine
49:55 Margin Debt Could Accelerate a Market Selloff
53:17 How to Navigate the Risks Ahead
FINANCIAL DISCLAIMER:
The information contained in this video and the resources available for download through our affiliated website are not intended as, and shall not be understood or construed as financial advice, nor should it be interpreted as a solicitation to sell or an offer to sell investment advisory services. No person who currently works for or contracts with Peak Prosperity or Peak Financial Investing is an attorney or accountant, nor are we holding ourselves out to be, and the information contained in the video and on the website is not a substitute for legal or tax advice from a professional who is aware of the facts and circumstances of your individual situation. While Peak Financial Investing is a registered investment advisor, please note that this podcast is not intended to be investment advice.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability, or completeness of, nor liability for, decisions based on such information, and it should not be relied on as such. We have done our best to ensure that the information provided is accurate and provides what we feel is valuable information. The views expressed are subject to change based on market and other conditions.
No guests or clients appearing on the podcast receive any form of compensation for their appearance and obtain no other benefit from either Peak Prosperity or Peak Financial Investing.
All investing involves risks, including the possible loss of capital. Asset allocation and diversification do not ensure a profit or protect against loss. Please note that outperformance does not necessarily represent positive total returns for a period. There is no assurance that any investment strategy will be successful. All investments carry a certain degree of risk. Dividends are not guaranteed, and a company’s future ability to pay dividends may be limited.
Additional important disclosures for Peak Financial Investing may be found in our Form ADV Part 2A, which can be found at https://adviserinfo.sec.gov/firm/summary/319672.
 by cmartenson